Quantitative Financial Modeling and Market Research
This project focuses on applying data science and machine learning techniques to financial market analysis. The work includes collecting and processing market data, developing statistical and predictive models, evaluating trading signals, and building repeatable research workflows in Python.
Current areas of work include:
- Financial and market data collection, cleaning, and feature engineering
- Statistical modeling and exploratory analysis
- Machine learning models for prediction and classification
- Backtesting and evaluation of quantitative strategies
- Risk analysis and performance monitoring
- Development of reusable research and analytical tools
The project is organized around several ongoing Python / Jupyter Notebook workflows, with regularly generated analytical outputs used to evaluate model behavior, strategy performance, and market conditions over time.
The goal is to develop practical quantitative research systems that combine statistical reasoning, machine learning, software development, and financial analysis. Selected models and strategies are tested in live market environments using privately managed capital.
Tools and technologies include Python, Jupyter Notebook, pandas, NumPy, scikit-learn, statistical modeling libraries, financial data APIs, and custom data-processing and backtesting workflows.
Selected Outputs
Unstructured Data Viewer
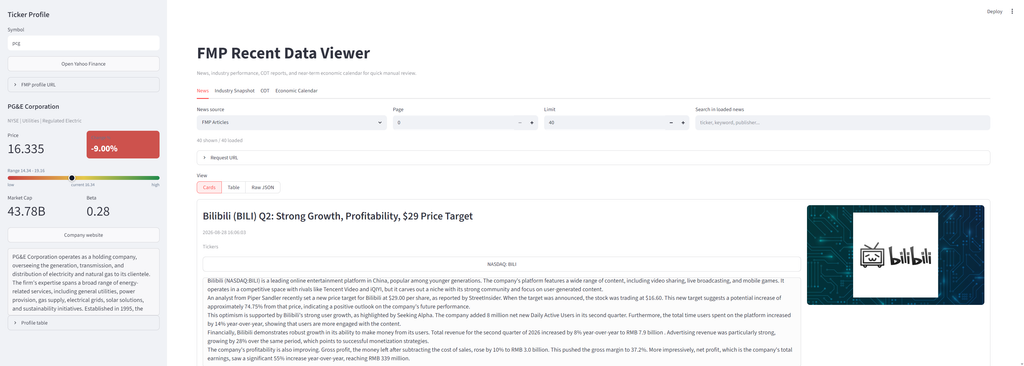
An interactive viewer for recent FMP data, including market news, industry snapshots, economic calendar views, COT data, commodity trend views, and ticker profile lookup. The app supports cached API calls, saved focus lists, request URL inspection, and downloadable tables.
Daily Model Picks
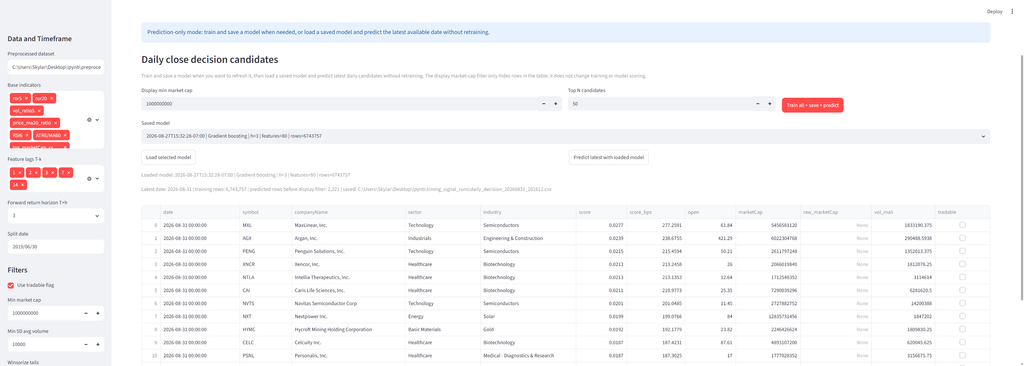
A time-series stock timing research app using lagged technical, liquidity, volatility, score, and market-cap features. The app supports lag-feature scans, gradient boosting / ridge models, out-of-sample IC evaluation, quantile return curves, rolling stability charts, daily decision candidates, saved models, and latest-date prediction.
Multi-Factor Dashboard
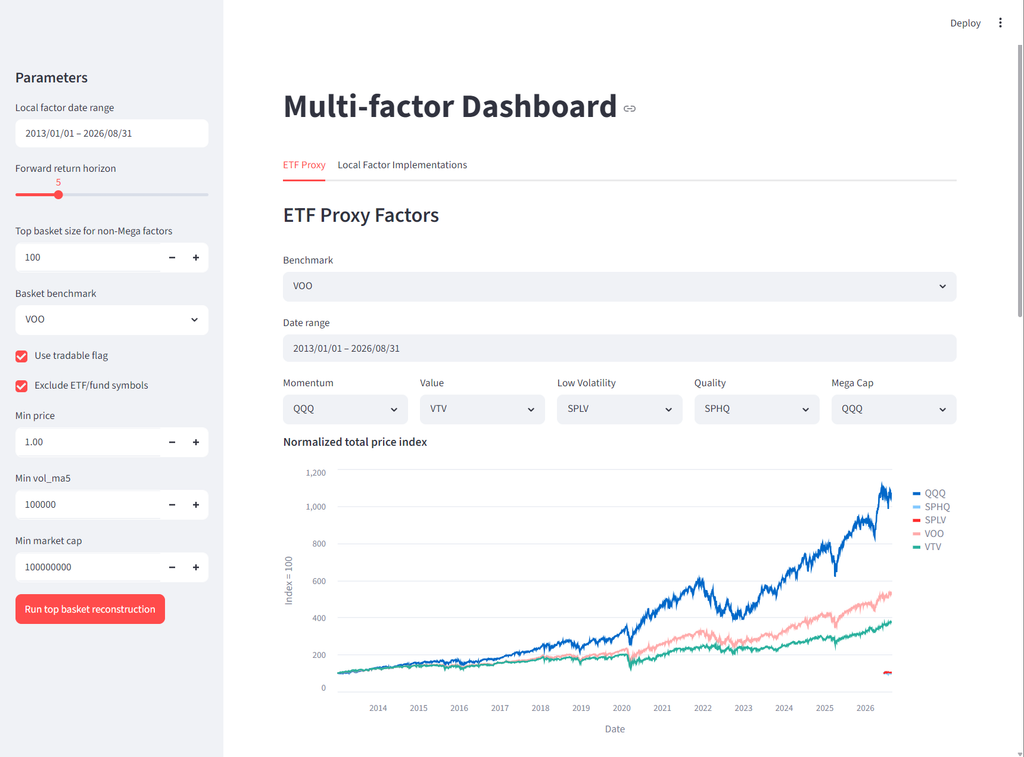
A multi-factor dashboard for ETF proxy factor comparison, local top-basket factor replication, weekly rotation preview, benchmark comparison, and simple machine-learning factor selector training and prediction.
Quick Feature/Factor Backtest
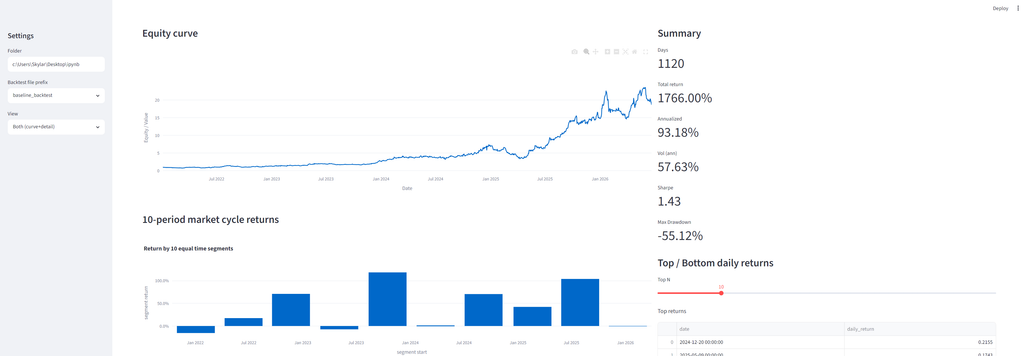
A configurable LightGBM backtest runner for selecting split dates, objectives, features, regularization parameters, and portfolio construction settings. The app runs model training/backtesting and displays command output, equity curve, daily details, and feature importance.